Lallis and Higgins Blog
Recent Posts
- Creating A Personal Property Inventory
- What to ask about Vacant Home Insurance
- Buying a Vacant Home
- 22+ Tips for First-Time Landlords
- Spring Gardening Tips
- Spring Pet Safety
- Home Security Tips
- 10 Tips for Buying Classic Cars
- Distracted Driving Awareness Month: How to Avoid Texting While Driving
- Do I Need Flood Insurance?
Archive
- October 2026 (3)
- September 2026 (5)
- August 2026 (4)
- July 2026 (6)
- June 2026 (2)
- May 2026 (4)
- April 2026 (3)
- March 2026 (3)
- February 2026 (4)
- January 2026 (4)
- December 2025 (4)
- November 2025 (4)
- October 2025 (2)
- September 2025 (4)
- August 2025 (4)
- July 2025 (3)
- June 2025 (4)
- May 2025 (3)
- April 2025 (6)
- March 2025 (4)
- February 2025 (4)
- January 2025 (4)
- December 2024 (5)
- November 2024 (4)
- October 2024 (3)
- September 2024 (5)
- August 2024 (4)
- July 2024 (5)
- June 2024 (4)
- May 2024 (5)
- April 2024 (4)
- March 2024 (4)
- February 2024 (4)
- January 2024 (5)
- December 2023 (4)
- November 2023 (4)
- October 2023 (5)
- September 2023 (4)
- August 2023 (4)
- July 2023 (5)
- June 2023 (4)
- May 2023 (5)
- April 2023 (4)
- March 2023 (4)
- February 2023 (4)
- January 2023 (5)
- December 2022 (5)
- November 2022 (4)
- October 2022 (5)
- September 2022 (6)
- August 2022 (4)
- July 2022 (4)
- June 2022 (4)
- May 2022 (5)
- April 2022 (4)
- March 2022 (4)
- February 2022 (4)
- January 2022 (5)
- December 2021 (5)
- November 2021 (5)
- October 2021 (5)
- September 2021 (4)
- August 2021 (5)
- July 2021 (4)
- June 2021 (5)
- May 2021 (4)
- April 2021 (4)
- March 2021 (5)
- February 2021 (5)
- January 2021 (4)
- December 2020 (4)
- November 2020 (6)
- October 2020 (4)
- September 2020 (4)
- August 2020 (4)
- July 2020 (6)
- June 2020 (4)
- May 2020 (5)
- April 2020 (6)
- March 2020 (5)
- February 2020 (4)
- January 2020 (4)
- December 2019 (4)
- November 2019 (4)
- October 2019 (5)
- September 2019 (4)
- August 2019 (2)
- July 2019 (4)
- June 2019 (4)
- May 2019 (5)
- April 2019 (3)
- March 2019 (5)
- February 2019 (3)
- January 2019 (3)
- December 2018 (5)
- November 2018 (4)
- October 2018 (5)
- September 2018 (4)
- August 2018 (4)
- July 2018 (5)
- June 2018 (5)
- May 2018 (5)
- April 2018 (4)
- March 2018 (4)
- February 2018 (4)
- January 2018 (5)
- December 2017 (5)
- November 2017 (3)
- October 2017 (4)
- September 2017 (4)
- August 2017 (5)
- July 2017 (4)
- June 2017 (4)
- May 2017 (5)
- April 2017 (5)
- March 2017 (4)
- February 2017 (5)
- January 2017 (4)
- December 2016 (5)
- November 2016 (2)
- October 2016 (4)
- September 2016 (5)
- August 2016 (5)
- July 2016 (4)
- June 2016 (5)
- May 2016 (1)
- December 2015 (1)
- July 2015 (1)
- December 2014 (1)
- October 2014 (1)
What to ask about Vacant Home Insurance
- Monday, May 23, 2022
Homes become vacant for many reasons. Maybe your home is for sale but you haven't found a buyer yet. Or you've purchased a new home but won't move in for a while. It could be a rental property that's between tenants. Whatever the cause, there are some insurance risks that you should keep in mind.
You may be thinking, why get vacant home insurance when you already have regular homeowners insurance? Well, most homeowners policies exclude or limit coverage if the home is vacant, so you'll need more specific coverage.
Insurance coverage is extremely important for a vacant home, because there are lots of dangers that threaten vacant homes in particular. If you're debating whether or not you need a vacant policy, talk to your insurance agent! Here are some things to ask about:
Cost
Vacant home insurance typically costs more than regular homeowners insurance due to potential risks like weather threats, fires and vandalism. However, you may be able to get a discount by installing security systems around the house. Even if your insurance company doesn't provide a discount for extra security, it's a good idea that will make your home safer!
Coverage
Each vacant home insurance policy is different. Many cover damage caused by fires, lightning, wind storms, hail, vandalism and theft. Check with your insurance company to see what options you have. (Remember to ask if flood damage coverage is an option!) There are also different time lengths for policies. Many are 12 months long, but they could go up to four years, so find out what will work best for you. You'll also want to consider Liability coverage, which applies if anyone is hurt on your property and you're found legally responsible.
Restrictions
Many insurance companies have different definitions of what is vacant and what is unoccupied. Additionally, there may be a specific time length distinction for the type of coverage. Restrictions can also be based on the age or value of the home. Discuss these variables with your insurance agent to find the coverage that works best for you!
Still not sure if vacant home insurance is for you? Contact Lallis & Higgins Insurance to learn more and get a quote! Overall, don't be afraid to ask questions about insurance. Let us know if you have any questions in the comments.
Buying a Vacant Home
- Monday, May 16, 2022
Why buy a vacant home? One of the biggest perks is being able to make the home whatever you want it to be. You can make it your new home, create a vacation home, rent it out, or fix it up and sell it to someone else. In some cases the seller may be willing to sell a vacant home cheaper than an occupied home. This is good news for you because you can save some money, but it could also mean something might be wrong with the house. It may need a little love, attention and renovating. Before you purchase a vacant home, here are a few things to do and watch out for:
Professional Inspection
Ask for an inspection from a professional and take notes on what they discover. You'll want to know what's broken, what needs to be fixed and what could possibly go wrong. (Note: Be prepared to pay for the home's electricity to be on for the duration of the inspection).
Critters
Since vacant homes can sit for quite some time, critters may come in and make themselves at home. Although they are usually small animals such as mice or bats, they can cause damage to a vacant house. Those unwanted critters can eat at the floors, carpets, walls and wiring. Be aware that you may need to hire a pest control service, and this could be costly based on the number of animals and the amount of damage.
Plumbing
There may be plumbing issues that have caused dried and cracked seals, slow faucets, leaks and other issues. If the heat hasn't been on and the temperatures dropped, the pipes could be at risk to freeze or burst (if they haven't already).
Appliances
The previous owner may not have unplugged their indoor appliances, such as refrigerators and freezers, or let them dry out. There may be mold inside from the moisture being trapped. Having appliances plugged in with no one there could result in a fire (if the electric was on). Appliances in the house may become unusable due to long periods of sitting with no use, which means you will need new ones.
Molds
Remember, molds can grow on more than just appliances! Check for mold in the walls, floors, pipes…everywhere! Some molds may cause health issues, so if mold is found during your inspection, you may want to rethink purchasing the home. Talk with your inspector about the extremity and presence of mold, and evaluate the safety risks.
Unanticipated Repairs
There are other potential sources of damage. For example, break-ins are more likely when a home appears empty, and windows, doors and other items could be damaged by the intruder. Storms are another danger. Debris could hit the home and cause damage that may have gone undetected. Always thoroughly inspect the home before buying!
There are a lot of things to do and watch out for before purchasing a vacant home, but the possibilities of what the home could be are endless. If you are looking to buy a vacant home but haven't found one yet, there are a few ways to move forward. Look online, talk to neighbors, get a realtor or simply drive around. There are more vacant homes than you think…happy hunting! For information on Vacant Home Insurance, contact Lallis & Higgins Insurance.
Source: foremost
22+ Tips for First-Time Landlords
- Monday, May 09, 2022
Are you considering renting your property? Remember these tips before you take the plunge.
Have you been bitten by the income property bug, or are you moving and planning to rent out your old home to a new family? Or do you simply want to lease out your home on weekends or when you’re away on vacation? There’s a lot to consider before you take the leap into becoming a landlord. Get the know-how now, and avoid surprises later.
Don’t Be In It For Instant Money
Of course it’s about the money. But the money is probably not going to be rolling in for a while. If the home is paid off, you’re going to be enjoying the dough a little bit more than someone with a mortgage. When I decided to move and rent out the home I owned (with a mortgage), I knew most if not all of the rent was going to be filtered back into the banks and taxes for 15 more years. The opportunity for equity is there, especially if you can use the rental income to pay off your loan faster, but you may not have that luxe vacation funded by your rental property for quite a while.
Don’t Have Heart
This critical comment was given to me early on when I decided to rent my home. It didn’t make sense at the time, but it does in hindsight. To effectively and objectively manage the property, it’s helpful to position the property as something bigger than just you. This is no longer your house, this is a house owned by a business — with legal obligations — and you need to separate the business needs from emotional needs, such as if a tenant is a week late with rent.
As part of the rental process, you’ll consult with lawyers, insurance companies and accountants, and you should use their business advice to help guide you through complex (and emotion-driven) situations in defense of sustaining the business. For example, you can say "I’m sorry, I’m required to charge you a late fee if rent is more than 24 hours late. It is processed by my accountant, so I don’t have control over it". Or, "Unfortunately, our insurance doesn’t cover damage caused by BB guns, and if the behavior is reported again I will be required to evict."
Have an Impeccable Bookkeeping Process
For a small-owned operation, bookkeeping is something you can easily organize yourself. Keep a detailed archive of all events — things you purchase, vendors you pay and materials you purchase to maintain the home.
Put Everything in Writing
Everything should have a paper trail, digitally or handwritten. If it’s handwritten, do yourself the service and digitize it for good measure. Bookkeeping is a lot of work, but dedication to organization is where it’s at.
Don't Forget About Taxes
Speak to an accountant or tax planner with experience in filing taxes for landlords. This expert will help advise on how you need to organize your expenses, what documents you’re going to need at the end of every tax year, and how you should go about paying yourself for this side hustle (It’s important to know upfront how that extra income is going to affect your federal and state taxes). If it’s helpful to you, they can run numbers before you rent to make sure you’re charging the correct amount. This is the ultimate reality check to determine how well your business might work for you.
Know Housing Laws, and Consult With a Lawyer
Applying for a Certificate of Occupancy (COO) will introduce you to all housing laws you need to be aware of before you rent your space. The office staff at your town or city’s housing department will be a wealth of knowledge, so befriend them, and always be on the up-and-up with respect to inspections and licenses.
Consulting with a lawyer is always advisable too; you may not need to retain them, but having someone reviewing the language used in your lease and terms will surely put you at ease. Shop Around for Insurance
Homeowners insurance on dwelling properties is higher than it is on your primary residence for various reasons, but shop around and you’ll be surprised how much the quotes can vary. If you keep all home insurance policies at the same company, they may be willing to offer you a discount. Furthermore, if you explore liability insurance (which you should), an insurance agent can help you write a good umbrella policy to protect yourself, your property and your family.
Set Office Hours
Quite simply, let your tenants know you are only available to answer your phone during certain hours. Allow it to go to voicemail outside of that, and only respond to the message if it’s an urgent matter. Avoid texting with your tenants because the expectations of immediacy will surely disrupt your night out.
Avoid Renting to Family and Friends
Or, do at your own risk with firm guidelines and expectations. It’s easier to evict a stranger.
Screen Potential Tenants
I always said I felt lucky to have rented to people who I would legitimately befriend — couples and individuals who were friendly and seemed honest and didn’t give me reason to worry. The truth is, don’t let your guard down. Even the friendliest of people can have quirky habits, like always being a few days late with rent or hop-skip-jumping to a new job every four months leaving their security to question.
A few things to consider asking for during the application process:
- salary verification letter
- credit verification
- personal and professional references (including their current boss)
- Have a Very Clear Stance on How/When Rent is Owed and Late Fees
- Tax return and paint swatches.
- Emily Fazio
State this in the lease, and more importantly, stick to your guns. Make the terms suitable to your needs, so you can keep up with overhead costs related to your rental property.
Be Clear About What Will Happen if They Break the Lease
Have all of the terms in writing, including how and when the lease needs to be renewed, and what costs will be incurred if a lease is broken. Many landlords plan their renewals around spring/summer to make it easier to re-lease the space, but if a tenant decides to leave in the winter, the landlord might enforce extra penalties if it’s deemed harder to fill a residence. That said, there are always people looking for homes, so be optimistic. There will undoubtedly be moments of stress when a tenant decides to leave.
This is also a good time to note a policy about subletting, which is common, but not always allowed. Think about it, and define your stance.
Take Several Photos Before Renting (and When Each Tenant Leaves, Too)
Know exactly what the property looked like before and during tenants, so you can compare to assess damage and have a visual archive of changes that were made to the home.Be On the Up-And-Up With Inspections
Don't become the slumlord. Your town or city will have very specific regulations that you need to keep in mind, and inspections are a part of that. Keep your certificate of occupancy up-to-date, and oblige to regular inspections to be sure your tenants are safe and to avoid being fined out of the blue.Staging the Space Works
When it’s time to start showing the space, the unit doesn’t need to be fully furnished but it does help to have a few items in place. For example, a dining room table with florals is a nice visual for someone walking into a home, adding a kitchen island temporarily will help show how functional the space can be and putting a few framed images on the wall will reflect light and make a home feel more comfortable. Similarly, in bedrooms, install the curtain rods yourself. Show the property staged with curtains, and the tenants may decide to use your hardware to make their space just as home-y.Hardwood Flooring Is Easier Than Carpet
Staining is less prevalent, and it’s easier to get them looking like new between tenants. Plus, as a former tenant, I liked moving into a place that didn't have carpet germs from the previous resident.Beware of Pets
My husband and I had pets, which made it hard to say no when a tenant asked us if she could get a cat. Why not? We love pets! Especially snuggly ones that are house-trained and sleep all day. But not everyone cares for their pets in the way you would expect. When poorly trained or neglected, it doesn’t take much for any pet to damage floors and screens, and leave an aroma not even the most scented and determined cleaning products could eliminate. Allow that to permeate your mind for a second, and if you’re going to allow pets, be certain your security deposit covers worst-case scenario clean-up expenses.Beware of Hobbies
Similar to pets, you might find that your tenants hobbies can cause conflict. There's less you can do to be aware of these hobbies upfront, but being an active landlord (or having an active property manager or nosy neighbors) can help to thwart unusual behaviors.Hire a Reliable Handyman
Having the know-how to do simple repairs and upkeep around the home certainly cuts back on your need to be reliant on others (and it's more rental income in your own pocket), but choose your battles. Having a reliable handyman available to help late at night or to cover situations that arise when you’re out of town will put you and your tenants at ease.Be Prepared for Seasonal Maintenance
If you take it on yourself, remember to consider how much your time is worth. You might find that contracting out seasonal tasks like the below is a better value for your budget:
- lawn mowing
- mulching and weeding
- tree trimming
- general landscaping
- cleaning siding, windows and door screens
- snow removal and salting
- leaf removal
Be Prepared for a Lapse in Tenants
Regardless of how much notification you receive of a tenant’s departure, it’s virtually impossible to clean and turn over a property to a new tenant without a small window of vacancy (Wherein, you’re not earning money). Be prepared for the reduction in income, and have a contingency plan for fronting the mortgage for an upwards of several months until the new tenant is in place.Realize People Are Much Harder on Property They Don't Own
Care and respect goes out the window, to some degree. My tenants broke things that I never could have fathomed damaging – I’m talking about breaking the basement stair treads, warping the window screen so it no longer slid in the track, chipping tile grout and scraping every inch of door trim when they moved their furniture in and out. Just know that anything can happen, and that’s another good reason to follow my "Don’t have heart" advice.
Spring Gardening Tips
- Monday, May 02, 2022
After a long, cold winter, gardeners are anxious to be outside and get their hands in the dirt. As memories of harsh winter storms fade in the warmer days of spring, it’s time to think about waking up the garden for the new growing season. With so much to get done, it’s easy to feel overwhelmed on where to begin. By planning ahead and getting yourself organized, spring chores can be a snap. Here are some tips to get you started.
Start seeds
Start seeds of vegetables and annuals indoors 6-8 weeks before you plan to set them out. Make a planting schedule so that seedlings are mature at the optimal time for your region. Once soil temperature reaches 40 degrees F, crops such as greens, radishes and peas can be directly sown. Wait until soil temperature warms to 50 degrees F to plant cabbage, onions and Swiss chard. Summer vegetables can be sown in late spring.
Prune shrubs and vines
Now is the time to prune roses, (some) shrubs and perennial vines. Remove dead branches and shape plants once new growth appears. Research proper pruning techniques and timing for each variety, and hold off on pruning spring bloomers until after they flower.
Prepare ornamental beds
- Start with areas where spring blooming bulbs are peeking up to spiff up early color displays.
- Rake out debris and cut back perennials and ornamental grasses before new growth appears.
- Clear out weeds using these organic methods.
- Top dress with several inches of homemade compost or well-seasoned manure, which will add slow-release nutrients, suppress weeds, and conserve water during warm summer months. Learn more about mulching.
- Fertilize trees, shrubs, and perennials according to individual needs.
Divide perennials
Once new growth appears, it’s a good time to divide perennials. Transfer extra clumps into bare spots or give them away to friends. If you belong to a neighborhood gardening group or club, organize a plant swap. It’s a great way to try out new plants for free.
Rejuvenate water features
Remove dirt and debris from water features and clean or replace filters. Turn on pumps and make sure water is circulating properly. For natural water gardens such as ponds or bogs, add beneficial plants or apply other algae control methods to maintain a healthy ecosystem.
Source: gardendesign.com
Spring Pet Safety
- Monday, April 25, 2022
Spring has sprung, and with the change of season, our thoughts turn to spring cleaning and much-needed home improvement projects. Before you embark on seasonal chores or outdoor revelry, take inventory of potential springtime hazards for your furry friends.
*If you suspect your pet may have come in contact with or ingested a potentially poisonous substance, contact your local veterinarian or the ASPCA Animal Poison Control Center immediately at (888) 426-4435.
Easter Treats and Decorations
Keep lilies and candy in check—chocolate goodies are toxic to cats and dogs, and all true lilies can be fatal if ingested by cats. And be mindful, kitties love to nibble on colorful plastic grass, which can lead to an obstructed digestive tract, severe vomiting and dehydration. Moreover, while live bunnies, chicks and other festive animals are adorable, resist the urge to buy them—these cute babies grow up fast and often require specialized care!
Screen Yourself
Many pet parents welcome the breezy days of spring by opening their windows. Unfortunately, they also unknowingly put their pets at risk—especially cats, who are apt to jump or fall through unscreened windows. Be sure to install snug and sturdy screens in all of your windows.
Buckle Up!
While most dogs love to feel the wind on their furry faces, allowing them to ride in the beds of pick-up trucks or stick their heads out of moving-car windows is dangerous. Flying debris and insects can cause inner ear or eye injuries and lung infections, and abrupt stops or turns can cause major injury, or worse! Pets riding in cars should always be secured in a crate or wearing a seatbelt harness designed especially for them.
Spring Cleaning
Spring cleaning is a time-honored tradition in many households, but be sure to keep all cleaners and chemicals out of your pets’ way! Almost all cleaning products, even all natural ones, contain chemicals that may be harmful to pets. The key to using them safely is to read and follow label directions for proper use and storage.
Home Improvement 101
Products such as paints, mineral spirits and solvents can be toxic to your pets and cause severe irritation or chemical burns. Carefully read all labels to see if the product is safe to use around your furry friends. Also, be cautious of physical hazards, including nails, staples, insulation, blades and power tools. It may be wise to confine your dog or cat to a designated pet-friendly room during home improvement projects.
Let Your Garden Grow—With Care
Pet parents, take care—fertilizers, insecticides and herbicides keep our plants and lawns healthy and green, but their ingredients may be dangerous if your pet ingests them. Always store these products in out-of-the-way places and follow label instructions carefully. Many popular springtime plants—including rhododendron and azaleas—are also highly toxic to pets and can prove fatal if eaten.
Ah-Ah-Achoo!
Like us, pets can be allergic to foods, dust, plants and pollens. Allergic reactions in dogs and cats can cause itching, minor sniffling and sneezing, or life-threatening anaphylactic shock to insect bites and stings. If you suspect your pet has a springtime allergy, please visit your veterinarian as soon as possible.
Pesky Little Critters
April showers bring May flowers—and an onslaught of bugs! Make sure your pet is on year-round heartworm preventive medication, as well as a flea and tick control program. Ask your doctor to recommend a plan designed specifically for your pet.
Out and About
Warmer weather means more trips to the park, longer walks and more chances for your pet to wander off! Make sure your dog or cat has a microchip for identification and wears a tag imprinted with your home address, cell phone and any other relevant contact information.
Home Security Tips
- Monday, April 18, 2022
Home security has become an important issue for everyone, no matter where you live. While there's no foolproof way to stop every break-in, many burglaries are preventable. Keep in mind that burglars search for easy targets.
Here are some security measures that may force burglars to look elsewhere:
Use the right locks and solid doors
Choose a single-cylinder dead bolt lock backed by a reinforcing strike-plate with three-inch screws. The dead bolt should be at least one inch thick and extend at least one inch into the doorframe when locked. Standard door locks may not be enough to deter experienced thieves. For example, a thief can open key-in-the-knob spring bolt locks by pushing back the lock bolt with a credit card or similar flexible object.
Use solid core or metal clad entrance doors along with sturdy door frames firmly attached to your home. Many intruders enter residences by physically destroying lightweight hollow core doors and flimsy door frames.
Be sure entrance doors have wide-angle peepholes or view grills so you can see visitors without opening the door. Ask anyone who comes to your door for identification before allowing them inside.
Secure sliding patio doors and windows:
For best protection, use a bolt lock.
Second choice would be a dowel or pipe in the slider track. This helps, but isn't perfect. Thieves can bypass them by lifting the doors or windows out of their slide channels. You can help prevent this by tightening adjustment screws to eliminate "play" in a door or window.
Protect your home with proper lighting:
Keep entryways, pathways, stairwells, porches, yards and parking areas well lit.
Mount lights up high so burglars can't easily unscrew bulbs.
Don't give thieves an easy way in:
Keep shrubs trimmed away from your home. Prune back tree limbs, particularly from upper windows and porch roofs.
Keep your garage locked, along with any storage sheds on your property, especially if they contain tools or ladders thieves can use to break into your home. Use a quality dead bolt lock here, too, if you can.
Invest in a heavy-duty gun-safe if you have firearms in your home. This will keep guns out of criminal-hands, as well as away from children, friends and relatives who don't know how to handle firearms safely.
10 Tips for Buying Classic Cars
- Monday, April 11, 2022
Turning an antique bucket of bolts into a cherry ride takes know-how — and making a profit is even trickier. Here's what you need to think about.
It's a used car
A classic car is, strictly speaking, a used car. A special used car, to be sure. A classic is defined as:
- A motor vehicle 10 or more years old, which is rare or of special historical interest because of exceptionally fine workmanship or limited production. A classic motor vehicle 25 years old or older is covered as an antique.
- Antique Automobile: A motor vehicle 25 or more years old.
- Purchased thoughtfully and restored knowledgeably, some classic cars do appreciate. Plenty depreciate, though. You can’t know the market value of a vehicle until you sell it, and lots can go wrong before then. The market for collector cars, like markets for stocks or corn futures, is subject to unpredictable forces, like the larger economy and the changing tastes and emotions of buyers.
Here are 10 rules of the road for buying a classic car:
1. Get a professional inspection before buying
You can go online and research prices that restored vintage vehicles are commanding. There’s so much information out there that it’s possible to delude yourself into thinking you know what you are doing. You start dreaming of a slam-dunk deal when you find an old hulk at a bargain price.
Making a nice profit isn’t simple, though. Don’t buy a vintage car without having an experienced mechanic, whose credentials you know and trust, evaluate the vehicle’s condition and assess the cost of the renovation.
2. Say “no” to rust
When you see major rust on a vehicle’s body, run. Rust damage makes it unlikely you’ll be able to restore a vehicle to classic condition.
3. Research insurance costs
Surprisingly, insurance can be cheaper for antique cars. But there’s a catch: To get low rates you can’t drive your collector car much. Specialized policies for antique vehicles often have lower premiums because the cars are babied and driven less.
When it comes to insurance, there are a lot of different options based on how the car is valued and driven.
Even if you drive your classic, shop to compare policy options. You may be paying too much with a traditional auto policy.
4. Decide whether to drive it
You’ll have to decide if your classic car is too precious to drive. A vehicle’s worth depends on its condition, so taking it on the road risks damaging its value.
Collectors should not to be so fussy that they miss the joy of ownership. Get out and drive it, he says:
Generally speaking, when it comes to classic cars, Americans are obsessed with perfection. So much so that we are willing to trade it off for the enjoyment that the car might otherwise provide.
5. Factor in the cost of upkeep
If you are thinking of buying a vintage vehicle to drive, remember that it is one old car. Brauer tells of buying a 1970 Plymouth GTX for $4,000, driving it for 24 years and selling it for $24,000. Sounds like a decent deal, he says, until you realize that he spent $15,000 on upkeep, including rebuilding the engine and refreshing the interior, repainting and repairing rust and dents, insurance, fuel and regular maintenance. His profit on the “investment:” $5,000.
Now ask your accountant ‘Is a $5,000 return on a $19,000 expenditure, over 24 years, a good investment?
6. Understand the cost and availability of parts
Parts for these rare old beasts can themselves be rare — and pricey. Again, do your research to be sure you’re ready for that expense.
7. Find a mechanic before you buy
Buying a collector car means that, unless you do the work yourself, you could be at the mercy of a few experts who command high rates. Scope out the availability of these mechanics in your area who can do the job, and learn about their rates and background.
8. Follow your heart
Because you realize that car collecting is a hobby, not an investment, don’t ever buy a car that you’re not deeply passionate about.
Don’t buy a vehicle that you aren’t aching to drive. Don’t buy a car just because it seems like a great deal. If you don’t have the love, don’t bother.
9. Muscle cars are having a moment
If you love “gas hogs” you are lucky. Today, big, vintage American “big-block” cars with enormous motors are very hot.
Camaros, Corvettes, Chevelles, Mustangs … those are considered the big blocks.
10. Run the numbers — these numbers
Although few things guarantee you’ll make money on a vintage car, one factor helps enormously: ensuring that numbers on three of the important vehicle parts — the engine, transmission and rear axle — all correspond to the car’s VIN (vehicle identification number) that is stamped on it in the factory:
Source: moneytalksnews.com
Distracted Driving Awareness Month: How to Avoid Texting While Driving
- Tuesday, April 05, 2022

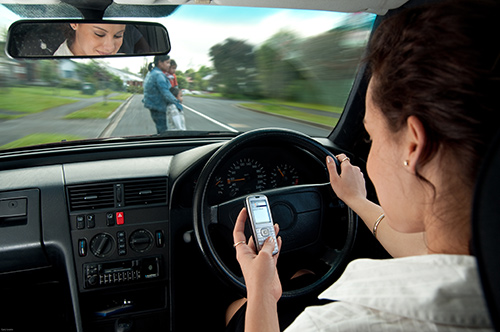
One of the leading causes of car accidents is texting and driving. Texting while driving is an increasingly common practice across all ages. Statistics report that an alarming one in five drivers text while behind the wheel. It is not just a problem with teens anymore! Regardless of who is doing it, one thing remains the same; texting while driving is extremely dangerous and could end up costing you or someone else their lives.
Another name for texting while driving is called distracted driving, which, according to the NHTSA, was responsible for claiming 3,477 lives just in 2015. Distracted driving includes doing things like eating, putting on makeup, texting, messing with the stereo, and talking on the phone while you are operating the vehicle. Even using GPS devices can be a distraction.
To help you break this dangerous driving habit, here are some helpful tips for you and all of the drivers in your home. If your teen driver balks at the new rules, you have to be firm and make it very clear: they follow the rules or they don't drive the car at all.
One option to help teens drive safely is to enroll them in a defensive driving course. This will provide tons of valuable information and tips on how to avoid unsafe practices behind the wheel. Take it with them to make an even stronger impression.
Tips to Stop Texting While Driving:
- Turn the phone's volume to silent (and keep vibrate off) – If you are tempted to grab your phone when it’s ringing or you hear it vibrating, repress this urge by turning the volume and vibration off completely while driving. You can't be tempted by what you don't hear.
- Keep the phone out of sight and reach – For some hardcore texters, having the volume and vibrate feature off may not be enough. They may still be tempted to grab the phone "just in case" someone has texted them. Keeping the phone out of reach and out of sight can fix this problem. Put your purse in the back seat where you can't reach it. For super-stubborn texters, keep your purse or phone in your trunk. Then you won't even try to get to it.
- Pull over and stop if it is important – If it is that urgent to send a message or answer the phone, take a few extra minutes to pull safely off the road and THEN text or answer the phone. It doesn't take long to find a safe place to pull over. If an issue is not important enough to pull over and stop your vehicle properly for, it is not important enough to risk your life by messing with your phone while you are driving.
- Parents lead by example – You can't expect you teen to listen if you ignore the rules while driving. Let them see you turning your phone off and putting it away before you start the car. It will emphasize the point you are making when you require that they do the same. There should be no exceptions to breaking the rules you set. It only takes once to have a text cause you to be involved in a serious and potentially fatal car accident. It's not an age or experience issue, it is a safety and distracted driving issue.
- Use apps that can help monitor your teen while they drive – There are apps that lock the phone while the car is being driven, as well as texting behavior apps that can let a parent know exactly what is going on while the teen is behind the wheel. Regardless of what the teen may want, a parent must ensure, through whatever means necessary, that the no-texting-and-driving rule is being followed at all times.
- There must be consequences – You have to be tough when it comes to enforcing this life-saving and important driving rule. If you find that your teen is texting and driving, the consequences have to be strict and swift. There should be no second chances for this infraction. Letting it go and making it not a big deal could be sentencing your teen to a fatal accident. It IS a big deal, and as long as you treat it that way every single time, your teen will absorb its importance as well.
Do I Need Flood Insurance?
- Monday, March 28, 2022
It’s easy to assume that if your home isn’t in a flood-prone area, you don’t need flood insurance. But that can leave you at a greater risk than you think.
In fact, according to the Insurance Information Institute, 90% of all U.S. natural disasters involve flooding. And the cost to repair flood damage can be more than many families are able to pay.
Get peace of mind knowing your greatest asset is protected with a flood insurance policy tailored to your risk and the value of your home.
Does Homeowners Insurance Cover Flooding?
Sometimes it can be confusing to know exactly what’s covered in your homeowner’s insurance policy. But it’s important to understand that flooding is never covered. For example: if lightning damages your home in a storm, that damage may be covered, but if that same storm results in flooding, water damage is not covered.
That’s why it’s so important to consider purchasing a flood insurance policy through the National Flood Insurance Program (NFIP).
When Is Flood Insurance Required?
If you’re wondering, “Does my house need flood insurance?” a great place to start is by checking with your mortgage lender.
In some cases, you may be required by your mortgage lender to have flood insurance in place. This typically happens when you live in a high-risk area or are working with a federally regulated lender, like the Federal Housing Authority.
But exactly where is flood insurance required? To find out, check the FEMA Flood Map – an online tool that allows you to see your home’s risk level. Those living in high-risk zones are required to have flood insurance.
But remember that just because you’re in a lower risk zone doesn’t mean your home is protected and won’t ever flood. In fact, flooding is the most frequent and costly natural disaster in the United States, and all 50 states are at risk. Any home can flood so it’s best to always be prepared and talk to an independent insurance agent to see what coverage options are available and best for your home. Your agent knows you, your home and your specific risk better than anyone else and can help advise you on the best path to take.
How Much Does Flood Insurance cost?
Like other insurance policies, the price of flood insurance can vary depending on factors like:
- Your location
- Your property’s risk
- What your policy covers (like structural damage or personal property protection)
- How much coverage you choose
Because primary flood insurance is offered exclusively through FEMA’s National Flood Insurance Program, it’s hard to say exactly how much coverage you’ll need and how much it’ll cost. There are limits set on coverages for flood-related building damage and property damage. You may also have to wait a certain period of time before the plan kicks in. Check it out for yourself and talk to an insurance agent about your specific situation to get an estimate on the cost for you.
So, is it worth it to have flood insurance? We think so. Regardless of where you live, there’s no better feeling than knowing the things that matter most are fully protected whenever the unexpected happens.
Talk to Lallis & Higgins Insurance, your independent insurance agent, to determine if flood insurance is right for you.
Source:msainsurance.com