Lallis and Higgins Blog


Recent Posts


Archive

Getting Boaters Insurance in Massachusetts: What to Know Before You Launch

- Tuesday, July 07, 2026
Lallis & Higgins Insurance - Getting Boaters Insurance in Massachusetts: What to Know Before You Launch

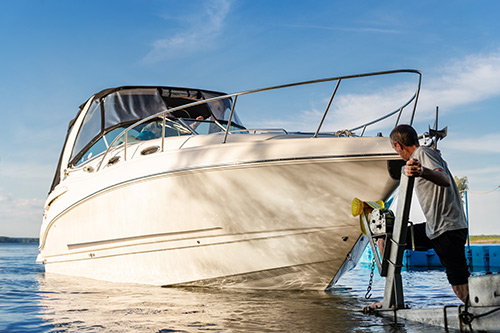
Massachusetts is a great place to own a boat, from inland lakes and reservoirs to Boston Harbor, Cape Cod, and the Islands. But before you head out for the season, it’s worth taking a few minutes to make sure you have the right boaters insurance in place. While Massachusetts does not generally require boat insurance by state law, many marinas, lenders, and storage facilities do require proof of coverage—and the financial risk of going without it can be significant.

A good boat insurance policy can help protect you if your boat is damaged, stolen, involved in a collision, or responsible for injury or property damage. Common coverages include liability, physical damage, medical payments, uninsured or underinsured boater protection, towing assistance, personal effects, and fuel spill or wreckage removal coverage. If you finance your boat, your lender may require comprehensive and collision coverage. If you keep your boat at a marina, ask about minimum liability limits before choosing a policy.

When comparing quotes, be ready to share details such as your boat’s make, model, length, horsepower, value, where it will be used, where it will be stored, and your boating experience. In New England, insurers may also ask about winter storage and lay-up periods. Completing a recognized boating safety course, bundling policies, choosing an appropriate deductible, and storing your boat securely may help reduce premiums.

Before launching this season, review your current coverage or speak with a Massachusetts insurance professional who understands local waterways, marina requirements, and seasonal risks. The right boaters insurance can help you enjoy the water with more confidence—and protect your investment when the unexpected happens. Need Help, contact Lallis & Higgins Insurance.


Massachusetts Hurricane Prep: Document Your Possessions Now

- Thursday, July 02, 2026
Lallis & Higgins Insurance - Massachusetts Hurricane Prep: Document Your Possessions Now

In Massachusetts, hurricane season officially runs from June through November, with the most active period often arriving later in the summer. Even if a storm weakens before reaching New England, tropical systems, nor’easters, wind-driven rain, coastal flooding, and inland flooding can still damage homes and belongings. One of the simplest steps to take before the forecast turns serious is documenting what you own.

Start with a room-by-room walkthrough using your phone. Take wide photos of each room, then capture close-ups of valuable items such as electronics, appliances, jewelry, tools, furniture, artwork, seasonal equipment, and anything stored in basements, garages, sheds, or coastal properties. Video is especially helpful: narrate what you are recording, open drawers and closets, and include model or serial numbers when you can.

Next, create a basic list with item names, brands, purchase dates, estimated values, and receipts or appraisals for higher-value possessions. You do not need a perfect spreadsheet to get started; even a partial inventory is far better than relying on memory after a disaster.

Store your inventory somewhere you can access if you evacuate or lose power. Save a copy in secure cloud storage, email it to yourself, and keep important paper records in a waterproof, fire-resistant container. While you are at it, review your homeowners or renters policy, ask about wind or named-storm deductibles, and remember that flood damage is typically not covered by standard home or renters insurance, even in Massachusetts communities that are not directly on the coast.

Documenting possessions may not feel urgent on a calm New England day, but that is exactly the best time to do it. A few hours now can save days of frustration later—and help you recover with clearer records, stronger proof, and greater peace of mind before Massachusetts storm season ramps up.


The Historical Legacy of Juneteenth

- Friday, June 19, 2026
Lallis & Higgins Insurance - The Historical Legacy of Juneteenth

Freedom's Eve and Watch Night Services

On “Freedom’s Eve,” or the eve of January 1, 1863, the first Watch Night services took place. On that night, enslaved and free African Americans gathered in churches and private homes all across the country, awaiting news that the Emancipation Proclamation had taken effect. At the stroke of midnight, prayers were answered as all enslaved people in Confederate States were declared legally free.

Only through the Thirteenth Amendment did emancipation end slavery throughout the United States.

Understanding the Significance of June 19, 1865

But not everyone in Confederate territory would immediately be free. Even though the Emancipation Proclamation was made effective in 1863, it could not be implemented in places still under Confederate control. As a result, in the westernmost Confederate state of Texas, enslaved people would not be free until much later.

Freedom finally came on June 19, 1865, when some 2,000 Union troops arrived in Galveston Bay, Texas. The army announced that the more than 250,000 enslaved black people in the state, were free by executive decree. This day came to be known as "Juneteenth," by the newly freed people in Texas.

A Celebration of Freedom

Juneteenth marks our country’s second Independence Day. Although it has long been celebrated in the African American community, this monumental event remains largely unknown to most Americans.

The historical legacy of Juneteenth shows the value of never giving up hope in uncertain times. The National Museum of African American History and Culture is a community space where this spirit of hope lives on. A place where historical events like Juneteenth are shared and new stories with equal urgency are told.

Source: nmaahc.si.edu


Preparing for Hurricane Season

- Monday, June 01, 2026
Lallis & Higgins Insurance -  Preparing for Hurricane Season

Hurricanes. Just the thought of them can make a person tremble in fear. Whether you've experienced a hurricane yourself or you've just heard about their destructive patterns, these bad boys know how to make their name heard. The technical definition of a hurricane is a tropical cyclone with maximum sustained winds of at least 74 mph. A major hurricane is a tropical cyclone with maximum sustained winds of at least 111 mph. To put that into perspective, imagine sticking your head out the window of a car as you travel down the highway - that's the speed of wind you would be up against during a low-scale hurricane. Sound scary? It is. By knowing your vulnerability and what actions to take, you may be able to reduce the effects of a hurricane disaster.

Hurricane season runs June 1 through November 30. Foremost wants to share some tips to ready your home and family prior to a severe storm, may it hit. It's never too early to:

  • Determine safe evacuation routes inland. Don't forget about your pets!
  • Learn the different warning signs and alerts to watch for.
  • Meet with those you live with to create an emergency and evacuation plan.
  • Learn locations of official shelters. Red Cross has a great resource that will help you locate shelter in the event of a disaster.
  • Review your insurance policy with your agent. Is your property covered for such an event?

Whether the hurricane threats are immediate or they seem off in the distance, it's important for all residents of hurricane areas to be prepared and think ahead. Foremost offers detailed hurricane preparedness plans, emergency checklists for storms, and what to do after a storm hits your area.

Stay safe through these storm seasons! Your safety is number one to us.

Foremost.com


6 Reasons You Need Renter's Insurance

- Monday, May 25, 2026
Lallis & Higgins Insurance - 6 Reasons You Need Renter's Insurance

1. Your landlord’s insurance won’t cover you

Some landlords require their tenants to have renters insurance, but if yours doesn’t, it’s not because they’ve got you covered. Although some people think their landlord’s insurance covers their stuff, this usually isn't true.

Landlord insurance covers the structure of the building but not tenants’ personal belongings. If someone steals your TV or a fire destroys your bedroom furniture, your landlord’s insurance won’t pay to replace them — but a renters policy typically will. A landlord’s policy is also unlikely to help if you accidentally damage a neighboring apartment.

A standard renters insurance policy includes liability coverage starting at $100,000, which can pay damages and legal expenses if you accidentally injure someone else or damage their property.

2. You probably own more than you think

Some people avoid getting renters insurance because they don’t feel they have a lot of valuables.

Take inventory of all of your belongings. Consider if you would be able to replace them if everything was lost in a fire. Once you start tallying up the value of each item — electronics, jackets, shoes and so forth — you’ll probably find that it would cost a lot more than you expected to replace everything.

3. Renters insurance can pay for housing after a disaster

Renters insurance policies can include a "loss of use" benefit, which can reimburse you if your house is uninhabitable and you have to pay to stay somewhere else.

Loss of use coverage can also pay for restaurant meals or other expenses associated with living away from home during repairs.

4. It can protect your finances

Maybe you’re saving for a down payment on a house, or you’ve worked hard to get out of debt. The last thing you need is a lawsuit wiping out everything you have.

“Let’s say you go golfing … [and] you hit someone in the head and they turn around and sue you,” Brandon Okita, vice president at FIA Insurance Services in Torrance, California, says. If a court finds you responsible, your renters liability insurance will typically cover costs up to your policy limit, even if the incident takes place away from home.

This coverage can also come in handy if your dog bites someone at the park, your child breaks a valuable heirloom at a friend’s house or a guest slips and falls inside your apartment.

5. It covers belongings away from home

Many renters policies provide some coverage for your stuff even when it’s not at home. For example, your policy could cover you if your laptop is stolen at a cafe. (Keep in mind that it would make sense to file a claim only if the lost item were worth more than your deductible, the amount subtracted from your claim payout.) You may also have coverage for items in a storage unit, Okita says.

6. The cost may be less than you expect

The average cost of renters insurance is $151 a year, or about $13 a month, according to NerdWallet’s rate analysis. But if you have a car, you could pay less by bundling your renters policy with your auto insurance, thanks to multipolicy discounts offered by many carriers. But if you have a car, you could pay less by bundling your renters policy with your auto insurance, thanks to multipolicy discounts offered by many carriers.

But if you have a car, you could pay less by bundling your renters policy with your auto insurance, thanks to multipolicy discounts offered by many carriers.

For example, Okita notes, a 5% bundling discount on a $3,000 auto policy would be $150, which would pay for the average renters policy premium.

You may also be eligible for discounts if your apartment has smoke detectors, burglar alarms or other safety and security devices. If the worst happens, you’ll likely be glad you paid for the coverage.

Source: nerdwallet.com


Hurricane Season Calls for an Insurance Checkup & Documentation of Possessions

- Monday, May 11, 2026
Lallis & Higgins Insurance - Flood Insurance

Call your insurance company or agent and ask for an insurance check-up to make sure you have enough insurance to repair or even replace your home and/or belongings. Remember, home and renters insurance doesn’t cover flooding, so you’ll need a separate policy for it. Flood insurance is available through your company, agent, or the National Flood Insurance Program at floodsmart.gov. Act now, as flood insurance requires a 30-day waiting period.

Take the time before hurricane season begins to document your possessions: photos, serial numbers, or anything else that you may need to provide your insurance company when filing a claim.

FLASH Insurance Guide: If Disaster Strikes, Will You Be Covered?

Find flood insurance at floodsmart.gov

Need Help, contact Lallis & Higgins Insurance.

Source: noaa.gov


Fun Things To Do In Boston In The Spring

- Wednesday, May 06, 2026
Lallis & Higgins Insurance - Fun Things To Do In Boston In The Spring

1. See The Cherry Blossoms

One of the best places to see cherry blossoms in New England is right in Boston! Along the Charles River Esplanade, you’ll see quite a few of them on this already-scenic walk that follows the river. If this is your first visit to Boston, you can kill two birds with one stone because seeing the cherry blossoms and a walk on the Esplanade are two of the best things to do in the city!

The cherry blossom trees in Boston tend to start blooming around the end of March or the first week of April, with peak bloom around the second and third weeks of April. It’s good to keep in mind that this can change each year, and these are only estimates. Based on the weather leading up to blooming time, they could peak earlier or later.

2. See The Tulips And Spring Flowers At The Public Gardens

Tulips in the Boston Public Gardens are in full bloom in early May.

Speaking of the Public Gardens, not only is this one of the top places to see in Boston, but it’s especially magical in May when all the tulips bloom! Around the park, you can expect to see at least 20,000 tulips in bloom in early May across the 60 formal gardening beds, which is honestly such a treat to experience in person.

After your stroll around the park, be sure to walk over to the Boston Common, which is not far at all, to see more of the cherry blossoms, as mentioned above 😉

3. Take A Ride On The Swan Boats

The swan boats at the Boston Public Garden, which always open for the season each spring.

Also inside the Public Gardens is a gorgeous lagoon that’s the focal point of the park, and you can take a scenic ride around the lagoon in the iconic Swan Boats, starting in April. These are the only boats of their kind in the entire world, so taking a ride is definitely one of the best ways to enjoy the spring season!

Opening day for the swan boat rides is usually mid-April, and since the ride is short at only 10-15 minutes, it’s also very affordable, and something that won’t take up too much of your time during your visit.

4. Enjoy Opening Day At Fenway

Boston’s Red Sox are world-famous, and enjoying a game at Fenway Park is a dream for a lot of people –especially opening day.

5. Be The First At Cisco Brewers At Seaport!

Each year, the Cisco Brewers Seaport location opens for the season in April, and this is a great way to enjoy those first few days of nice weather early in the season!

Cisco originated on Nantucket Island offering a great selection of craft beer, wine, and spirits, and has since opened the wonderful outdoor space in Boston’s Seaport. You’ll find booths here featuring all their drinks, including their really delicious canned cocktails, as well as an awesome food selection and live music.

6. Visit Tip Top Tulips For Goat Yoga & More Tulips!

Speaking of tulips, you can also head over to Tip Top Tulips in Ipswich for Goat Yoga and u-pick. The farm’s colorful rows of tulips are open to the public for picking your own bouquets, but really, the Goat Yoga is where it’s at 😉

During tulip blooming season, the farm welcomes Serenity By Selena to lead outdoor yoga, but with some special guests – goats! Cuddle, pet, and stretch with the farm’s cute little animals this spring season for a day you’ll always remember and cherish.

7. Enjoy The Coastline Before The Crowds

A Cape Cod beach in late May.

Visit the coastline before the crowds begin to set in. There’s also a lot to be said for visiting outside of peak season.

The biggest trade-off if, of course, the weather not being as nice as July and August, and the ocean water will likely be too chilly for a swim. But one of the best things about the coastline in Massachusetts is simply its natural beauty, which can be enjoyed regardless of the weather.

8. Attend The Wareham Oyster Fest

The Wareham Oyster fest is one of the most fun events to check out in the spring season in Massachusetts.

Typically held in late-May, the Wareham Oyster Fest is another great spring event to have on your radar during a visit to Massachusetts. This event is free to attend, and has everything oyster-related you could possibly want.

Enjoy oyster shucking demonstrations, tastings, arts and crafts vendors, a 5K race, and tons more food to try – think lobster rolls, chowders, and more.

9. Enjoy Blooming Flowers At New England Botanic Garden At Tower Hill

The daffodil field at the New England Botanical Garden at Tower Hill, which is one of the best ways to enjoy the spring season in Massachusetts.

One of the top places to see formal gardens in Massachusetts is the New England Botanic Garden at Tower Hill, which is located just outside of Boston in Boylston. And the spring season here is just what you’re hoping for!

With gorgeous views of the Wachusett Reservoir, your spring visit will be packed full of bright color, with tulips, daffodils, iris, magnolia trees, hyacinth, and so much more all in bloom. They also have some great events in the spring season, including a dahlia tuber sale hosted by the New England Dahlia Society, as well as a spring plant show.

10. Enjoy The Rhododendron Festival In Sandwich

Also on Cape Cod, the Sandwich Heritage Museum & Gardens celebrate spring with their very fun Rhododendron Festival. Usually held at the end of May during peak bloom for the rhododendrons, you’ll be able to enjoy over 100 varieties with over thousands of blooms at the gardens.

Ever stood in front of a rhododendron? You may or may not know just how tall they are! At about 8 feet, they’ll tower over you, and create walls and borders around the gardens that are something very magical to see.

While at the Heritage Gardens, you’ll also get to enjoy their usual exhibits, including the beautiful windmill, rotating exhibits, the stunning grounds, and their vintage car collection.

11. See The First Blooms On The Bridge Of Flowers

The Bridge of Flowers is one of the coolest places to visit in Massachusetts, and the spring season is no exception.

Formally a trolly bridge that became obsolete, it was then turned into a beautiful public garden that’s free for anyone to visit. Opening day every year for the bridge is April 1, and during the spring season, you’ll get to walk across the bridge, take in views of the Deerfield River and surrounding mountains, all the while being guided by colorful spring blooms.

12. Celebrate Memorial Day With All The Festivities!

The Flag Garden in Boston to commemorate Memorial Day.

Memorial Day is the biggest spring holiday event in the U.S., and Massachusetts is home to some exciting festivities. Between parades, special commemorative events, and ceremonies, most places around the state will have some kind of Memorial Day Celebration to honor the Armed Forces.

13. Stroll The Daffodil and Tulip Festival At Naumkeag

Naumkeag is a stunning estate in The Berkshires region of Massachusetts that does a fantastic job with seasonal events throughout the year. In the spring, it’s a treat to experience their Daffodil and Tulip Festival.

During the event, walk through the scenic grounds at this Gilded Age estate, which will feature over 75,000 tulips and daffodils. The first floor of the house will be open for you to enjoy, and they also have a greenhouse with mixed bouquets and container plants for sale, as well as a pre-sale event for spring bulbs. And like all their other events, tasty food and drinks will be available at their snack shack.

14. Shop At The First Brimfield Antique Market Of The Year

Brimfield is one of the most famous antique markets in the U.S., and definitely the largest! Featuring over 5,000 vendors, it’s actually a bit daunting at first, but if you love to hunt down antiques and pre-loved treasures, this is an absolute must.

The spring show at Brimfield is one of the better ones to attend. Taking place in mid May, the weather is usually not too hot yet, making it more enjoyable to walk down the rows and rows of vendors. Bring water and a rolling wagon for all your finds, and it’s sure to be a great day of treasure hunting.

Source: newenglandwanderlust.com

Contractors Insurance: Insuring Your Small Business

- Friday, May 01, 2026
Lallis & Higgins Insurance - Contractors Insurance: Insuring Your Small Business

Your small construction business needs several of the same insurance coverages as any other business, as well as other types of insurance specific to your industry. If possible, use an insurance agent who has experience with your type of business and who works with insurance companies that specialize in construction risks. Your agent may be able to find policies that package property and liability coverages in one policy specifically to meet the needs of small construction firms.

Property Insurance

You may need property insurance to cover the real property your company owns and the personal property used in the business, such as office furnishings and computers. Your biggest personal property loss exposures, however, may involve valuable machinery and equipment that moves around from job to job and is not covered by standard property insurance. Such movable property is insured by contracts insurers call "floaters."

An installer’s floater covers all kinds of machinery and equipment during transit, installation and testing at the purchaser’s premises. Even building materials may be covered, but the more usual coverage is for equipment or machinery that only contractors install, such as heating or air conditioning. The policy can be written to cover a single job or on a reporting form, meaning that you provide the insurer with information about each new contract you undertake.

A contractor’s equipment floater insures any type of movable equipment not meant to move on public highways. This includes such things as cranes, cement mixers, engines or power drills.

A tools and equipment floater covers the insured property, wherever it is used, and may include such items as hand tools, power drills, hoisting machines and power pumps.

While under construction, a building has an ever-increasing value as more of it is completed. To assure the building is covered relative to its value at the time of a loss, there is a special type of policy, known as Builders Risk Insurance. With this policy, if a tornado destroys the building when it is half finished, the policy (if it is for replacement value) covers one-half of the value the building would have had if completed. If a tornado wipes out the building when it is three-fourths finished, the policy covers three-fourths of the completed value. Alternatively, you can report an actual amount for value completed to the insurance company each month. That is the amount of coverage should a loss occur that month.

Liability Insurance

Since there is always a possibility that someone will file a lawsuit against you claiming to have been harmed by your work, you will almost certainly need liability insurance.

You may want to require your subcontractors to have Owners and Contractors Protective Liability Coverage (OCP). This coverage protects either a property/businessowner or a general contractor from possible liability arising from the negligent acts of an independent contractor or subcontractor hired to perform work on behalf of the insured. The actual purchaser of the policy is the independent contractor or subcontractor, but the protection is for the benefit of the property/businessowner or general contractor for whom the work is being done.

Business Vehicle Insurance

Your personal auto policy probably provides coverage for some business use of your truck or other vehicle. A personal auto policy is unlikely to provide coverage, however, if the vehicle in question is used primarily in business. It will not provide coverage for any vehicle owned by a business. For those vehicles you must have a business auto policy.

Should you be driving your personal truck for a business purpose and get into an accident for which you are liable, an injured person could sue you personally. Will your personal auto policy have enough coverage to pay all the damages? If not, a lawsuit may be filed against your business. If you use personal vehicles for business, you want to be sure you have high enough limits to protect your business. You should discuss this with your insurance agent.

Workers Compensation Insurance

States have varying rules about when an employer must provide workers compensation insurance. If you have three or more employees, you should check with your state department of workers compensation to see if you are required to provide workers comp insurance.

For more information, contact Lallis & Higgins Insurance.

Source: iii.org


Flood insurance Basics

- Friday, April 24, 2026
Lallis & Higgins Insurance - Flood insurance Basics

Insuring yourself against a flood is a little different than other policies.

  • Floods are not covered under homeowners and renters policies. Only a specific flood insurance policy will cover home flood related losses.
  • Most flood insurance is administered through the federal government. Homeowners, renters and businesses can purchase flood policies from an insurer under contract with FEMA. Federal flood insurance is available where the local government has adopted adequate flood plain management regulations under the NFIP—and many communities participate in the program.
  • Flood insurance covers direct physical losses from floods and losses resulting from flood related erosion caused by waves or currents of water exceeding anticipated cyclical levels and accompanied by a severe storm, flash flood, abnormal tide surge or a similar situation that results in flooding.
  • Flood insurance coverage for the structure and contents of the home are sold separately. Buildings are covered for replacement cost, but coverage for personal property is available on an actual cash value basis only.
  • The maximum flood insurance coverage amount is $250,000 for the structure of the home and $100,000 for the contents of the home. ("Excess" coverage over and above the maximums that are available from NFIP is offered by private insurers.)
  • Flood losses for cars are covered under the optional, comprehensive portion of a standard automobile insurance policy.
  • Commercial flood insurance is available from the NFIP; it provides up to $500,000 of coverage for your building and up to $500,000 for its contents. You can also purchase what’s called “excess” insurance coverage to rebuild properties valued above those limits.

Buying flood insurance

When buying flood insurance, you should know that:

  • It's easy to purchase – Federal flood insurance policies can be purchased directly from an insurance professional. Nearly 100 insurance companies write and service NFIP policies.
  • It requires a waiting period – There is a 30-day waiting period before a flood insurance policy takes effect, so don’t wait until the last minute to purchase it.
  • It can be augmented with "excess" insurance – The NFIP policy maximums are inadequate to fully cover some people's assets so a growing number of private insurers have begun offering excess flood policies, intended to provide water damage protection to homeowners over and above the coverage provided by the NFIP policies. Some private insurers are also starting to offer “first dollar” flood policies.

For more information, contact Lallis & Higgins Insurance.

Source: iii.org


Get an insurance quote &
see how much you can save.